Wednesday, June 6, 2018

Ermitaño - a low key resource

We got a rather low-key PR from Evrim about the maiden resource at Ermitaño (link), which was surprising as there have been several PRs with some very good drill results recently (link).

Realistic metal prices....not!
This equates to approx. 3.5Mt @ 4.0 g/t Au and 68 g/t Ag or 4.93 g/t AuEq (358 g/t AgEq), which represents 95% of all new inferred resources found by First Majestic.

Lol
It looks very interesting, especially for an initial resource. However, there isn't  much information on the project, all we get is a simple plan map...

and a long section..

Low grade zones always are on a diet, whereas high-grade area (like small dogs) expand to fill as much space as possible...
These holes are very widely spaced (>100m), and have First Majestic inflated the tonnages by using a very big search radius (i.e. using all of the drill-hole data no matter how far apart they are)?

Here is a Leapfrog view of the data (link). I had to use trigonometry to estimate the hole lengths and dips, and so they will be a bit out.

My long section (looking north - east to the right). Showing DH intercepts and 50m, 100m and 200m radius buffers.
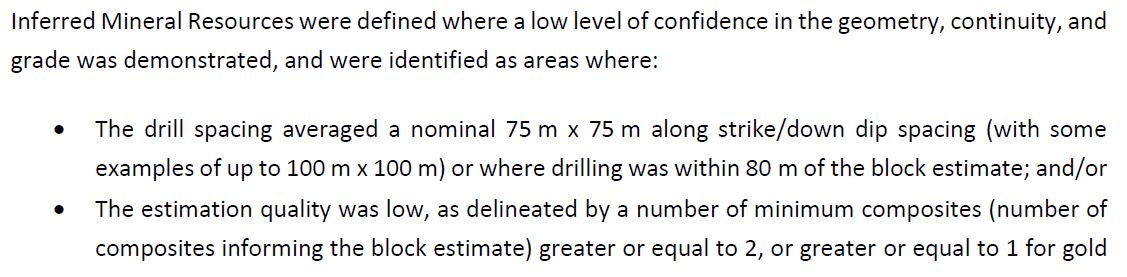
Drill-hole spacing to define a resource varies by the deposit style and metal distribution, so here are some examples for similar (Epithermal) deposits to see what they used for inferred resources:

La Guitarra - First Majestic


Los Gatos (Sunshine Precious Metals)


San Jose (Quintana Resources)


San Martin (First Majestic)


Santa Elena (First Majestic)


We can see that there are many different criteria, but in general we get:

  • Indicated Resources ~50m sample/drill-hole spacing
  • Inferred Resources >50m (but anything massively over 100m is unrealistic).

So First Majestic do seem to be pushing the limits for the resources limits at Ermitaño, nothing major, but a hole drilled between 06 and 10 would be a good idea to increase confidence, especially in the western area where the few, high-grade holes are >100m apart.

The fact that First majestic plan to drill 18,000m at Ermitano is very positive, it shows that they are confident in finding new zones and expanding on the known resources, but it would be nice to have a bit more information (e.g. where the heck is the Aitana vein located) showing targets and proposed exploration areas.


Saturday, June 2, 2018

Platosa - Mexico's highest cost silver mine


huuuuuuuuuuuuuuuuuuuuuuuuuugnn Platosa mmm mmmm MMMMMmmmm

Halve production and double costs
You could run out of lube reading through the drill results press releases (link, link, link, and link) and Kleenex while reading the PEA.

even the exchange rate works in their favour

An IRR of just 118% with some very conservative metal prices. This mine must make money hand over fist. So why have Brendan and his team raised ~C$41.6M since Q3, 2015?

  • C$6.6M in Nov 2015
  • C$2M in Osisko (Oban) shares for the DeSantis Property
  • C$3M in march 2016 from Sprott
  • C$15.2M in July 2016
  • C$14.8M in Sept 2017
According to the PEA, this mine should produce an embarrassing amount of money?

Let us check that visually, this is just a quick graph showing cumulative net profits or loss compared to cumulative funds raised.


Ohh, so they've actually made a cumulative loss of ~C$24M since mid-2015, with just 1 quarter (Q4, 2017) out of the past 11 where they have made a profit, and even after the "turnaround"

It is nice to see another successful mining company with a mine matching its PEA.

What is cool is, their current working capital is ~C$14.5M, which means that they have already started to chip away at the C$14.8M they raised last year, so hopefully with the Hecla lease they'll actually make some money before they have to raise some more.....


Tuesday, May 29, 2018

New Point - Majuba

Sometimes it is good to get someone to check your press release before it is sent into the wide blue yonder...


You know, maybe it would have been nice to have shown the column listing the gold assays?

Monday, May 28, 2018

AntaKori Update

I've been (slowly) working on a series of posts reviewing several porphyry projects, highlighting that many are very small or just too low grade to really bother with, but I decided to go back and update my AntaKori model, with the recent-ish drilling results (link) because I've had this nagging feeling that AK was the same - not quiet good enough.

I plotted its resources on the USGS Cu chart of doom with updated CuEq figures using Regulus' CuEq calculation shown intheir PRs, which, unlike the 2012 43-101, doesn't include any credits for Mo, Pb or Zn. Doing this decreases the overall CuEq grade from 0.92% to 0.83% CuEq.


So, my gut-feeling was wrong, AK is good enough, but has there been any change with the new drilling?

Here is an officially bad calculation for the AK resources that occur within the Regulus mineral licenses. You can get the Leapfrog viewer file here (link).


~11Mt extra tonnes at the same grade

That's disappointing, but the grade has stayed the same! Small victories!

Why wasn't there a drastic change? The drill results have been impressive, but unfortunately, the drilling has been directed by Coimolache who are focusing on extending the high-sulfidation gold mineralization they are mining to the west, and had not been focused fully testing the skarn-porphyry potential at AK.

However, hole AK-18-007 may be changing that. Most companies won't drill a 1400m deep hole costing ~$0.4M if it wasn't hitting something interesting (unless they needed a lot of novelty knife sharpeners for the Lima Gold Symposium). Unfortunately, we'll never see the results, but we can do some arm waving.

Here is the hole plotted against Kev 'n' Stu's geology section...

A 1400m drill-hole drilling nothing, I don't think so.... 
Oooooooohhhhh, the 700m interval that Regulus have seen, fondled and probably licked, lines up quite well with that flushed Miocene Porphyry (same age as Antamina - 900Mt @ 0.99% Cu) intrusion thrusting powerfully through the hard rocks of northern Peru.

Why don't we have a look how this hole relates to the other targets defined by Regulus?


I've borrowed the Intense magnetic image from the latest presentation, not just because it is pretty, but looking beyond the hot color stretch we can see that hole AK-18-007 was drilled between the 2 bestest-ist porphyry-skarn targets (# 1 and #2) on the property? Regulus already have a decent sized target that is basically the sweaty armpit of a well mineralized district. I'm hoping that they can get some rigs exploring the blue nipple (target 1) to see what is causing it.

The red-stuff is just skarn and no-one cares about that.....

Saturday, May 12, 2018

SolGold - Aguinaga - an initial review

DISCLOSURE - I OWN SHARES IN SOLGOLD

At last, some drilling away from Alpala (link)! SolGold have finished the first hole at Aguinaga (link). Unfortunately, I don't think the results will be very special, I'm guessing that they come in around the 0.4-0.6% CuEq level.

This is what we are told about the first hole:

Translation - feck, we hope it gets better at depth

It is very early days (1 hole), but the concern is that the Aguinaga Porphyry appears to be small and low grade. We see that the 'strongly mineralized porphyry' was intersected ~300m vertically below the discover which limits its extent to the NW and being just ~250m wide (horizontally) limits is potential to become huge. Bollocks!


The core photos from hole 01 look a bit anemic. They look similar to the low grade holes at Alpala, that typically ran around 0.5% CuEq (typically 0.3% Cu and 0.1-0.2 g/t Au)


At Alpala, if a drill hole was bulging with copper sulfides, Sol Gold would rush out an early release with partial results. They haven't done the same here, we get some confirmation of lack of optimism in the hole by the company in this statement.


i.e. the core looks crap, we're leaving the rigs to drill the good stuff

However, if we work back we know that the drilling would have passed through the 'well mineralized' porphyry around the start of April, so we should expect the results to be released before the end of the month if they are good enough to stand on their own. If they are below expectations, they'll be buried in a PR with a load of intercepts from Alpala.

I've created a separate Leapfrog project for Aguinaga, you can get the viewer file from here (link)


Thursday, May 10, 2018

Eldorado's Aura

I've found it, after centuries of searching, battling Nimbys, indigineous communities and shareholders, the source of the immense wealth of the Incas, but it is here (link) in Brasil.


Sweet mother of god, that is 168Moz Au, it is bigger than some inadequate deposits like:
  • Olympic Dam
  • Pebble
  • Grasberg
All of that in a company worth ~CND$65M, that is the bargain of the century...

but......

ooooooooooooooohhhhhhhhhhhhhhhhhhhhhhhhhhhhhhhh fuuuuuuuuuuuuuuuukkkkkkkkk, damn typos. just a bit further down the page......


only a 1000 fold error, good job no-one reads mining company websites.....

Monday, May 7, 2018

Almadex - annual return

I've received some comments on a post I wrote back in Jan 2017 on El Cobre (link). I haven't been following them but I was intrigued on why Newcrest were so interested (link). What has changed since my last post?

We've had some reasonable intercepts (link, link and link) over last year, so I thought, time to do an update as this project is ripe for an initial resource estimate. So here is my officially bad guesstimate:

Some gold, not much copper
So using a >0.4 g/t Au and >0.15% Cu cut-offs we get:
  • ~92Mt @ 0.68 g/t Au and 0.25% Cu or 1.08 g/t AuEq (or 0.68% CuEq).
  • or 2.03Moz Au and 160Kt Cu
Despite its name, El Cobre is in reality a gold deposit, but with ~2Moz @ ~0.7 g/t Au, is it good enough, especially when we have several, much larger deposits at a similar grade that are still sitting in the ground?

I want to look at the summary assay data in more detail, focusing on: 
  1. Current mineralization
  2. Expansion potential
  3. Potential problems
I'm ignoring any socio-political issues and just looking at the summary assay data. As always, you can download the Leapfrog viewer file from here (link).


Current Mineralization and exploration potential

Here is a plan map showing the 4 areas that have been drilled by Almadex.

Plan Map
Here are a couple of pseudo-long sections (looking Northwest)

Gold


Copper


You can clearly see that the highest grade and thickest (i.e. the 'best') intercepts are from Norte, with a bit of copper at Villa Rica/Raya Tembrillo and some bits 'n' bobs in the other areas.

An interesting observation, when we compare the known targets against the soil geochemistry.

Au - left; Cu - right
We can see that the best area drilled at El Cobre, the Norte Zone has a minimal associated geochem anomalies, just a single line (Line 75800 - page 37 in the technical report), with some robust Au, Cu and Mo anomalies. I would love to see a regional map of soil Mo data as there could be a few other targets that could be interesting but where the Cu in the soils has been leached away.

Norte Zone

The Norte zone has received the bulk of the drilling and given the best results so far.

Au - far left = plan map with section lines, center = section A-A'; right = Section B-B'

Cu - far left = plan map with section lines, center = section A-A'; right = Section B-B'


We can see that Norte has been well drilled, the Au-Cu mineralization is well defined, with some >1 g/t Au zones in the core of the deposit and grading out into a lower grade (>0.25 g/t) halo. The mineralization is well drilled with most continuation to the mineralization closed off. However, the Au in hole EC-17-026 is still open to surface and to depth and would represent a good area to put a couple of holes as this could expand the 'resources' by up to 25%.


El Porvenir

Another regional target that has seen limited drilling. The standout hole has been DDH-04CB1 (drilled in 2004) that intersected 298m @ 0.38 g/t Au and 0.16% Cu.

Au - far left = plan map with section lines, Center = section A-A' - Au; right = Section A-A' - Cu
 The follow-up drilling isn't as special, intersecting several thick low-grade (<0.25% Cu) copper mineralization with a few narrow higher grade Cu-Au zones (dykes?). There may be some potential to the SW (left), but overall the grades are low and for gold discontinuous.

Villa Rica/Raya Tembrillo

We've only had a few holes drilled into Villa Rica, so it is hard to have a definitive opinion.

Au - far left = plan map with section lines, Center = section A-A' - Au; right = Section A-A' - Cu
Form the drilling so far, we can see that Villa Rica is more copper rich, with thick low grade intercepts (<0.25% Cu) with higher grade Cu and Au mineralization restricted to narrow zones - better mineralized dykes or breccias? It was also interesting to see high-grade copper at/close to surface - are we seeing some supergene enrichment?

I feel that the drilling to date shows that the potential at Villa Rica is limited. The geochem data shows a large target, but this may be an erosion anomaly (i.e. copper weathering down-slope towards the streams to the east and south).


Encinal

This is the area where Almadex hit a high-grade gold vein in hole EC-16-008.

Top left = plan map; top right - section A-A' - Au; bottom right = section A-A' - Cu

Again, we see generally thin, scattered intercepts, but hole EC-17-025 did intersect a thick zone of low grade (<0.25%) copper mineralization that could be peripheral to a larger system to the East (right).

Potential Problems

The most obvious problem could be the metallurgy. I haven't seen any mention in in the technical report about any basic met-work. It would be nice to know the distribution and style of mineralization (e.g. is the gold all in sulfides, or is there a thick oxide zone etc..) as this could have a big impact on the processing (dump leach vs milling) and recoveries. If you're interesting here is a link to a decent paper on the subject (link).


Summary

Overall, outside of the Norte zone, most of the economic Au-Cu mineralization appears to be restricted to narrow scattered intercepts. There may be potential to the east in Encinal, but nothing that is indicative of a large, well mineralized porphyry system.

For me, I can't see where the project could be expanded to >5Moz Au that could lead to development, and the regional targets don't appear to offer any upside.